Efficiency Ratios Examples
Efficiency ratios compare what a business spends to what it uses. Read examples, a worked comparison, and why a clean figure hides the basis.
Efficiency ratios are often listed as a set of formulas, which hides the accounting choices behind each figure. The efficiency-ratio entry describes operating cost relative to revenue or assets, as the income-statement entry structures reported figures, as the profitability article explains accounting layers, as Earnings Quality: Accruals, Estimates, and Red Flags warns about clean numbers, as the publication standard forbids guaranteed outcomes.
Direct answer: Read efficiency ratios with the definitions, the period, and the business model behind them. Wikipedia's efficiency-ratio entry provides the concepts, and the income-statement entry covers reported figures. The boundary: a ratio is not cash generation, which the free-cash-flow article explains, as the publication standard forbids guaranteed outcomes.
Examples
Operating cost to revenue. How much of each revenue unit is consumed by operations, which the efficiency-ratio entry describes, as the income-statement entry structures the figures, as the profitability article explains the layers, as the comparables article requires consistent definitions, as the data-governance article requires dated figures, as the risk article requires residual risk, as the decision-memo article requires for a record.
Asset turnover. Revenue relative to assets, which the efficiency-ratio entry treats, as the balance-sheet entry covers the denominator, as the valuation article treats capital structure, as the EBITDA article explains what sits above and below the line, as the comparables article requires consistent definitions, as Earnings Quality: Accruals, Estimates, and Red Flags warns, as the data-governance article requires provenance, as the risk article requires residual risk.
Receivable and inventory days. How long cash is tied up, which the efficiency-ratio entry describes, as the cash-flow article treats working capital, as the inventory article treats stock as cash, as the time-series article warns about non-stationarity, as the monitoring article advises for review, as the rubric article requires concrete criteria, as the data-governance article requires dated figures, as the risk article requires residual risk.
The definition problem. The same ratio can use different numerators across firms, which the comparables article requires, as the income-statement and efficiency entries describe, as Earnings Quality: Accruals, Estimates, and Red Flags warns about clean figures, as the cash-flow article requires for reconciliation, as the data-governance article requires dated definitions, as the decision-memo article requires for a record, as the risk article requires residual risk.
Three consequences follow. Definitions come before comparison, as the comparables and data-governance articles require, as the income-statement and efficiency entries describe, as Earnings Quality: Accruals, Estimates, and Red Flags warns, as the cash-flow article requires, as the profitability article explains layers, as the EBITDA and valuation articles advise, as the balance-sheet entry covers the denominator, as the inventory and time-series articles advise, as the monitoring article advises for review, as the rubric article requires criteria, as the decision-memo article requires for a record, as the risk article requires residual risk.
A worked comparison
The following is hypothetical and illustrative. Two companies report the same operating cost ratio.
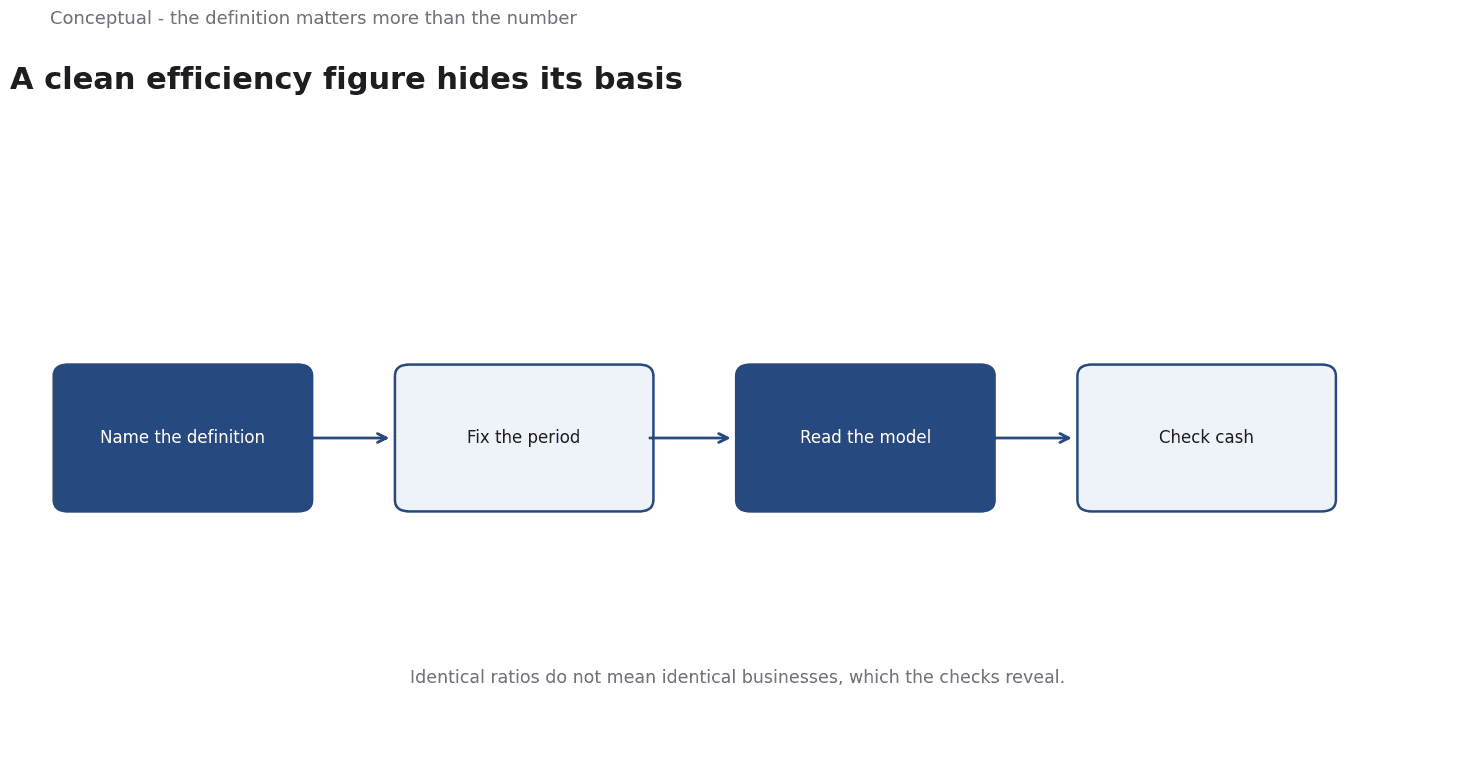
Three checks decide whether they are comparable. First, do they use the same numerator and denominator, as the comparables and efficiency articles require, with dated definitions, as data governance requires? Second, what sits in the operating line, as the income-statement and EBITDA articles explain, with a reconciliation, as the cash-flow article requires, as Earnings Quality: Accruals, Estimates, and Red Flags warns? Third, is the cash tied up in receivables or stock, as the cash-flow and inventory articles advise, with residual risk, as the risk article requires, as the decision-memo article requires for a record?
Three conclusions follow.
Identical ratios do not mean identical businesses, which the checks reveal.
Definitions matter more than the figure, as the comparables article advises.
And the decision should be recorded, as the decision-memo article requires.
What efficiency ratios cannot do
They cannot establish a cause, which the causal-inference article treats as a different question, as the correlation article warns about association, as the publication standard forbids guaranteed outcomes, as the risk article requires residual risk. They do not measure cash directly, which the free-cash-flow and cash-flow articles explain, as Earnings Quality: Accruals, Estimates, and Red Flags warns, as the comparables article requires consistent definitions, as the monitoring article advises for review. And they cannot remove the need to understand the business, which the company-analysis and value-proposition articles treat, as the decision-memo article requires for a record, as the risk article requires residual risk.
A decision test
- Check definitions, as the comparables article requires.
- Read each layer of the statement, as the income-statement entry advises.
- Reconcile to cash, as the cash-flow article requires.
- Check below-the-line items, as the EBITDA and profitability articles advise.
- Use dated figures, as data governance requires.
- Treat a clean figure as a question, as Earnings Quality: Accruals, Estimates, and Red Flags advises.
- Record the decision and residual risk, as the decision-memo and risk articles require.
For the accounting basis, see Reading Financial Statements; for the quality question, see Earnings Quality.
References & Further Reading
- Wikipedia contributors, 2026. Efficiency ratio - Wikipedia — Operating cost relative to revenue or assets.
- Wikipedia contributors, 2026. Income statement - Wikipedia — The structure of revenue, expenses and profit, and the difference between revenue and cash.